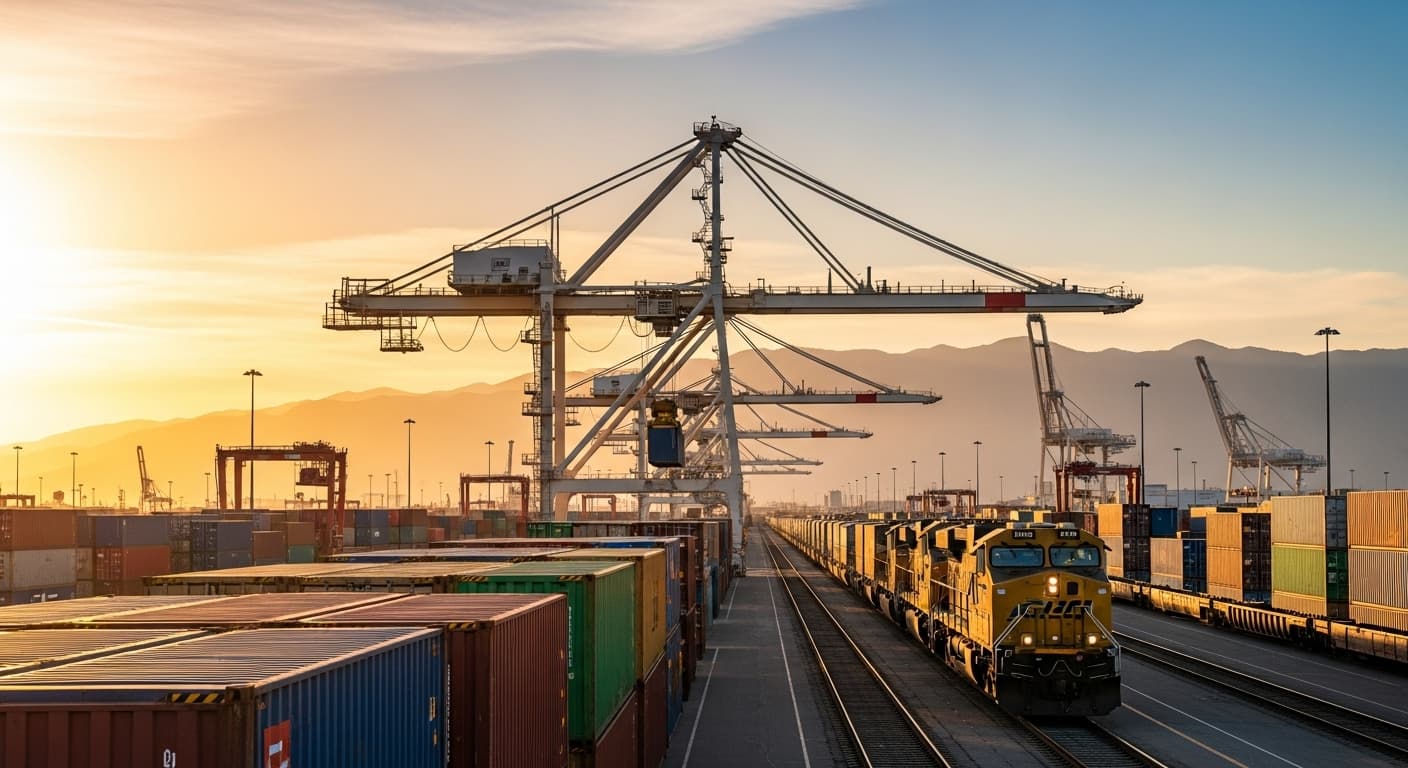
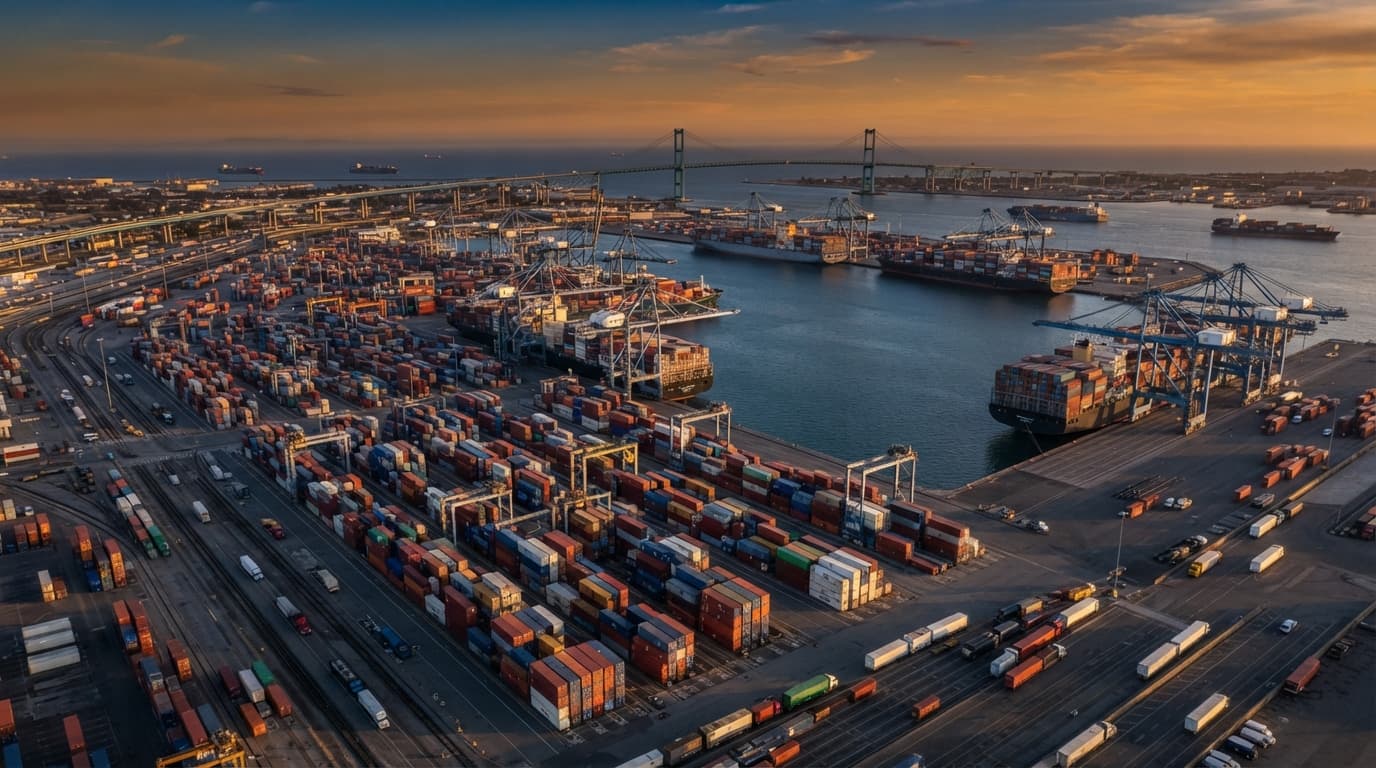
Executive Summary The Port of Long Beach handled 919,992 TEUs in August 2026, the busiest August in its 115-year history and the fifth-strongest single month on record, representing a 2% increase over August 2025. Imports rose 3.6% to 456,100 TEUs, exports increased 4% to 99,754 TEUs, and empty containers edged down 0.39% to 364,138 TEUs. Year-to-date through August, the port has moved 6,678,078 TEUs, up 1.3% compared to the same period last year. But the headline numbers obscure a more complex reality: much of the volume growth reflects tariff front-running rather than organic demand growth, and the extended peak season is colliding with record blank sailings that are tightening capacity. This analysis examines what the August numbers actually tell us and what logistics providers must do to prepare for the months ahead.
Port of Long Beach Posts Record August: What 919,992 TEUs Tells Us About the New Peak Season
(长滩港8月创纪录:919,992标箱背后的新旺季信号)
1 · The Numbers: A Record August by Any Measure
The Headline Figures
The Port of Long Beach’s August 2026 performance set multiple records:
| Metric | August 2026 | Change vs. August 2025 |
|---|---|---|
| Total TEUs | 919,992 | +2% |
| Imports | 456,100 TEU | +3.6% |
| Exports | 99,754 TEU | +4% |
| Empty Containers | 364,138 TEU | -0.39% |
| Year-to-Date (Jan–Aug) | 6,678,078 TEU | +1.3% |
Source: Port of Long Beach data, September 2026
A Historic Month
The 919,992 TEUs handled in August 2026 rank as the fifth-busiest month in the port’s 115-year history. Port CEO Dr. Noel Hacegaba framed the results in the context of a genuinely uncertain environment: “Our August numbers tell us that shippers continue to adapt to tariffs and geopolitical uncertainty and are confident in the Port of Long Beach’s ability to deliver,” he said. “The numbers also show that the Port is a safe and secure harbor that customers can count on.”
The Broader West Coast Context
Long Beach’s record August was part of a broader trend across the San Pedro Bay complex. The Port of Los Angeles processed 955,907 TEUs in August, capping the busiest three-month stretch in its history at over 2.9 million TEUs. Combined, the two ports handled nearly 1.9 million TEUs in August alone.
⚠️ Critical Takeaway: While the headlines celebrate record volumes, the underlying drivers are not purely organic growth. Understanding why volumes are elevated is essential to forecasting what comes next.
2 · The Drivers: Tariff Front-Running and Extended Peak Season
Tariff Front-Running: The Primary Catalyst
The most significant driver of elevated container volumes in 2026 has been tariff front-running—importers accelerating shipments ahead of anticipated tariff changes. Sea-Intelligence has specifically tied the Q2 surge to shippers racing to clear cargo ahead of the July 24, 2026 transition, when the temporary Section 122 global import surcharge expired and new Section 301 forced labor tariffs—covering roughly 60 economies—took effect the same day, an event we examined in detail in our earlier analysis of that transition.
According to Sea-Intelligence data, North America’s West Coast ports handled 3.7 million TEUs in Q2 2026, a 7.1% year-over-year increase. Critically, this growth was not driven by terminal demand recovery but rather by businesses rushing to stockpile goods before new tariffs took effect.
The pattern was particularly pronounced in May 2026, when port container throughput surged 12.7% year-over-year, with laden import volumes jumping 19.8%—the most concentrated front-running window of the year.
The Shift to Southern California
Notably, the front-running surge did not benefit all West Coast ports equally. New volumes concentrated heavily at the Ports of Los Angeles and Long Beach:
| Port | Q2 2026 Laden Import Growth |
|---|---|
| Los Angeles | +13.8% |
| Long Beach | +12.0% |
| Vancouver | -4.8% |
| Seattle-Tacoma (NWSA) | -9.2% |
| Prince Rupert | -12.4% |
Source: Sea-Intelligence, August 2026
Importers chose Southern California ports for their mature shipping routes, high vessel frequency, and stable customs clearance efficiency—ensuring goods could clear before new tariffs took effect.
The Extended Peak Season
The traditional peak shipping season—typically running from early summer through late summer or early fall—has been stretched significantly in 2026. Port CEO Hacegaba noted that high cargo numbers in what has already been a much longer peak season could extend into the first half of November.
The National Retail Federation’s Global Port Tracker now forecasts September as the busiest import month of the year, with volumes expected to reach 2.31 million TEUs—up 9.6% from September 2025.
Hacegaba attributed the extended peak partly to vessel delays caused by bad weather in China and ships diverting away from the Panama Canal amid concerns over potential drought conditions.
3 · The Hidden Risk: Record Blank Sailings and Capacity Crunch
The Contradiction
Here is the paradox at the heart of the August record: while ports are handling record volumes, ocean carriers are aggressively cutting capacity.
According to Project44 data, blank sailings—scheduled voyages that are cancelled—have soared to unprecedented levels:
| Route | Blank Sailings (2026) | Change vs. 2024 |
|---|---|---|
| China → U.S. West Coast | 67 | +46.5% |
| U.S. → China | 71 | — |
| U.S. West Coast → Southeast Asia | — | +75% |
| Southeast Asia → U.S. West Coast | — | +40.7% |
Source: Project44, via World Ports Organization
Bart De Muynck, senior supply chain analyst and former Gartner research lead, noted: “The current level of blank sailings by carriers is the highest since the initial phase of the pandemic. However, the strategic focus has shifted from crisis response to maintaining stable freight rates in a market distorted by tariffs.”
What This Means for Shippers
The combination of record import volumes and record capacity cuts creates a dangerous dynamic:
- Tighter capacity : Fewer available vessels mean higher spot rates and longer lead times
- Equipment shortages : Empty containers are lingering at ports, creating imbalances
- Congestion risk : Concentrated volumes at Southern California ports strain terminal operations
- Rate volatility : Carriers are managing capacity to support rates, not to meet demand
The Empty Container Paradox
Normally, a surge in imports would lead to a surge in empty container exports as empties are returned to Asia for refilling. But that is not happening in 2026.
Empty container movements at Long Beach actually fell 0.39% in August. As one industry analysis noted: “The chart highlighting the empty containers leaving the ports of Los Angeles and Long Beach shows there is no rush for empties to go back to be refilled” .
This is a red flag: if empties aren’t flowing back to Asia, it suggests that carriers are not expecting a sustained surge in future demand. The front-running surge is temporary, and carriers are positioning for a slower market ahead.
4 · The Intermodal Dimension: Rail Is Playing a Bigger Role
The Intermodal Moment
As tariffs and shipping route complications reshape supply chains, intermodal transit—moving containers using more than one mode of transportation—is becoming a more prominent option.
Anne Reinke, president and CEO of the Intermodal Association of North America, joined Hacegaba in a recent briefing and declared: “We are having an intermodal moment.”
The Sourcing Diversification Behind the Rail Push
In that same briefing, Hacegaba pointed to a specific reason rail investment now matters more than ever: sourcing is diversifying away from China, and Vietnam has become the Port of Long Beach’s second-largest trading partner, behind only China. As more companies diversify where they source and manufacture, cargo increasingly arrives from Southeast Asian origins that require longer ocean transit times to reach Long Beach. Efficient on-dock rail becomes correspondingly more important to offset that added transit time and keep total delivery speed competitive with alternative gateways.
The Pier B Investment
The Port of Long Beach is investing heavily in rail capacity to accommodate this shift. The $1.8 billion Pier B On-Dock Rail Support Facility is the centerpiece of the port’s rail capital improvement program, designed to shift more cargo to on-dock rail. Hacegaba has been direct about the payoff: “Pier B reduces processing time from four days to one.”
Construction began in 2024 and is anticipated to be completed in 2032. Moving cargo by on-dock rail is cleaner and more efficient, reduces truck traffic, and improves supply chain velocity.
Why This Matters
Rail is becoming a critical differentiator for West Coast ports competing for discretionary cargo. As Hacegaba put it: “Cargo follows a path of least resistance.” Ports that can move containers quickly from vessel to rail to inland destinations will have a competitive advantage—an advantage that matters even more as sourcing diversification pulls more cargo from origins farther from the U.S. West Coast.
5 · What This Means for Logistics Providers
1. Prepare for Continued Volatility
The August record is not a signal of sustained demand growth—it is a signal of tariff-driven timing shifts. Logistics providers should prepare for:
- Front-loading cycles tied to tariff deadlines
- Extended peak seasons stretching into November
- Sharp volume swings as policy changes take effect
2. Secure Capacity Early
With blank sailings at record levels, capacity is tight. Logistics providers should:
- Book space early for Q4 shipments
- Lock in rates where possible to avoid spot market volatility
- Develop relationships with multiple carriers to ensure redundancy
3. Monitor the Empty Container Signal
The decline in empty container movements is a leading indicator of future demand. If empties continue to linger at ports, it suggests that carriers are not expecting a sustained import surge. Logistics providers should monitor this metric closely.
4. Prepare for Inland Logistics Pressure
Concentrated volumes at Southern California ports create inland logistics pressure:
- Truck capacity may tighten
- Rail ramps may experience congestion
- Warehouse space may become scarce
Logistics providers should communicate proactively with customers about potential delays and cost increases.
5. Leverage the Intermodal Shift
The growing role of rail in port operations creates opportunities for logistics providers that can offer integrated intermodal solutions. Providers with rail expertise and relationships will be better positioned to serve customers seeking cost-effective, efficient routing.
6. Monitor Consumer Confidence
Hacegaba noted that consumer confidence appears to be softening, hitting levels that in the past have been associated with a recession coming within a year. If consumers pull back on spending, import volumes could decline sharply in 2027.
6 · Conclusion: A Record August, But for How Long?
The Port of Long Beach’s record August—919,992 TEUs, the busiest August in 115 years—is a remarkable achievement. But the record was built on tariff front-running, not organic demand growth.
Key Takeaways
| Factor | Detail |
|---|---|
| August 2026 TEUs | 919,992 (record August) |
| Import Growth | +3.6% to 456,100 TEU |
| Export Growth | +4% to 99,754 TEU |
| Year-to-Date | 6,678,078 TEU (+1.3%) |
| Primary Driver | Tariff front-running and extended peak season |
| Key Risk | Record blank sailings (67 China–USWC) tightening capacity |
| Leading Indicator | Empty container movements declining |
| Consumer Signal | Confidence softening |
The Bottom Line
The August record tells two stories. On the surface, it is a story of resilience—shippers adapting to tariffs, consumers continuing to spend, and ports handling record volumes. Beneath the surface, it is a story of policy-driven timing shifts and capacity management that may not be sustainable.
Logistics providers should celebrate the volume—but prepare for the volatility ahead. The extended peak season may stretch into November. But the record blank sailings and declining empty container movements suggest that the market is not as strong as the headline numbers imply.
The message is clear: Record volumes are not the same as sustained demand. Logistics providers that understand the difference will be best positioned to navigate the months ahead.
This analysis reflects Port of Long Beach August 2026 volume data released September 11, 2026, and related industry data from Sea-Intelligence, Project44, and the National Retail Federation. Specific volume forecasts and market conditions are subject to change. Logistics providers should monitor port data and carrier announcements closely for evolving conditions.